 Jesse Livermore
· 3 min read
Foris AG - 20ys too early (Burford Capital & Co)
Part of the Portfolio since 2020...
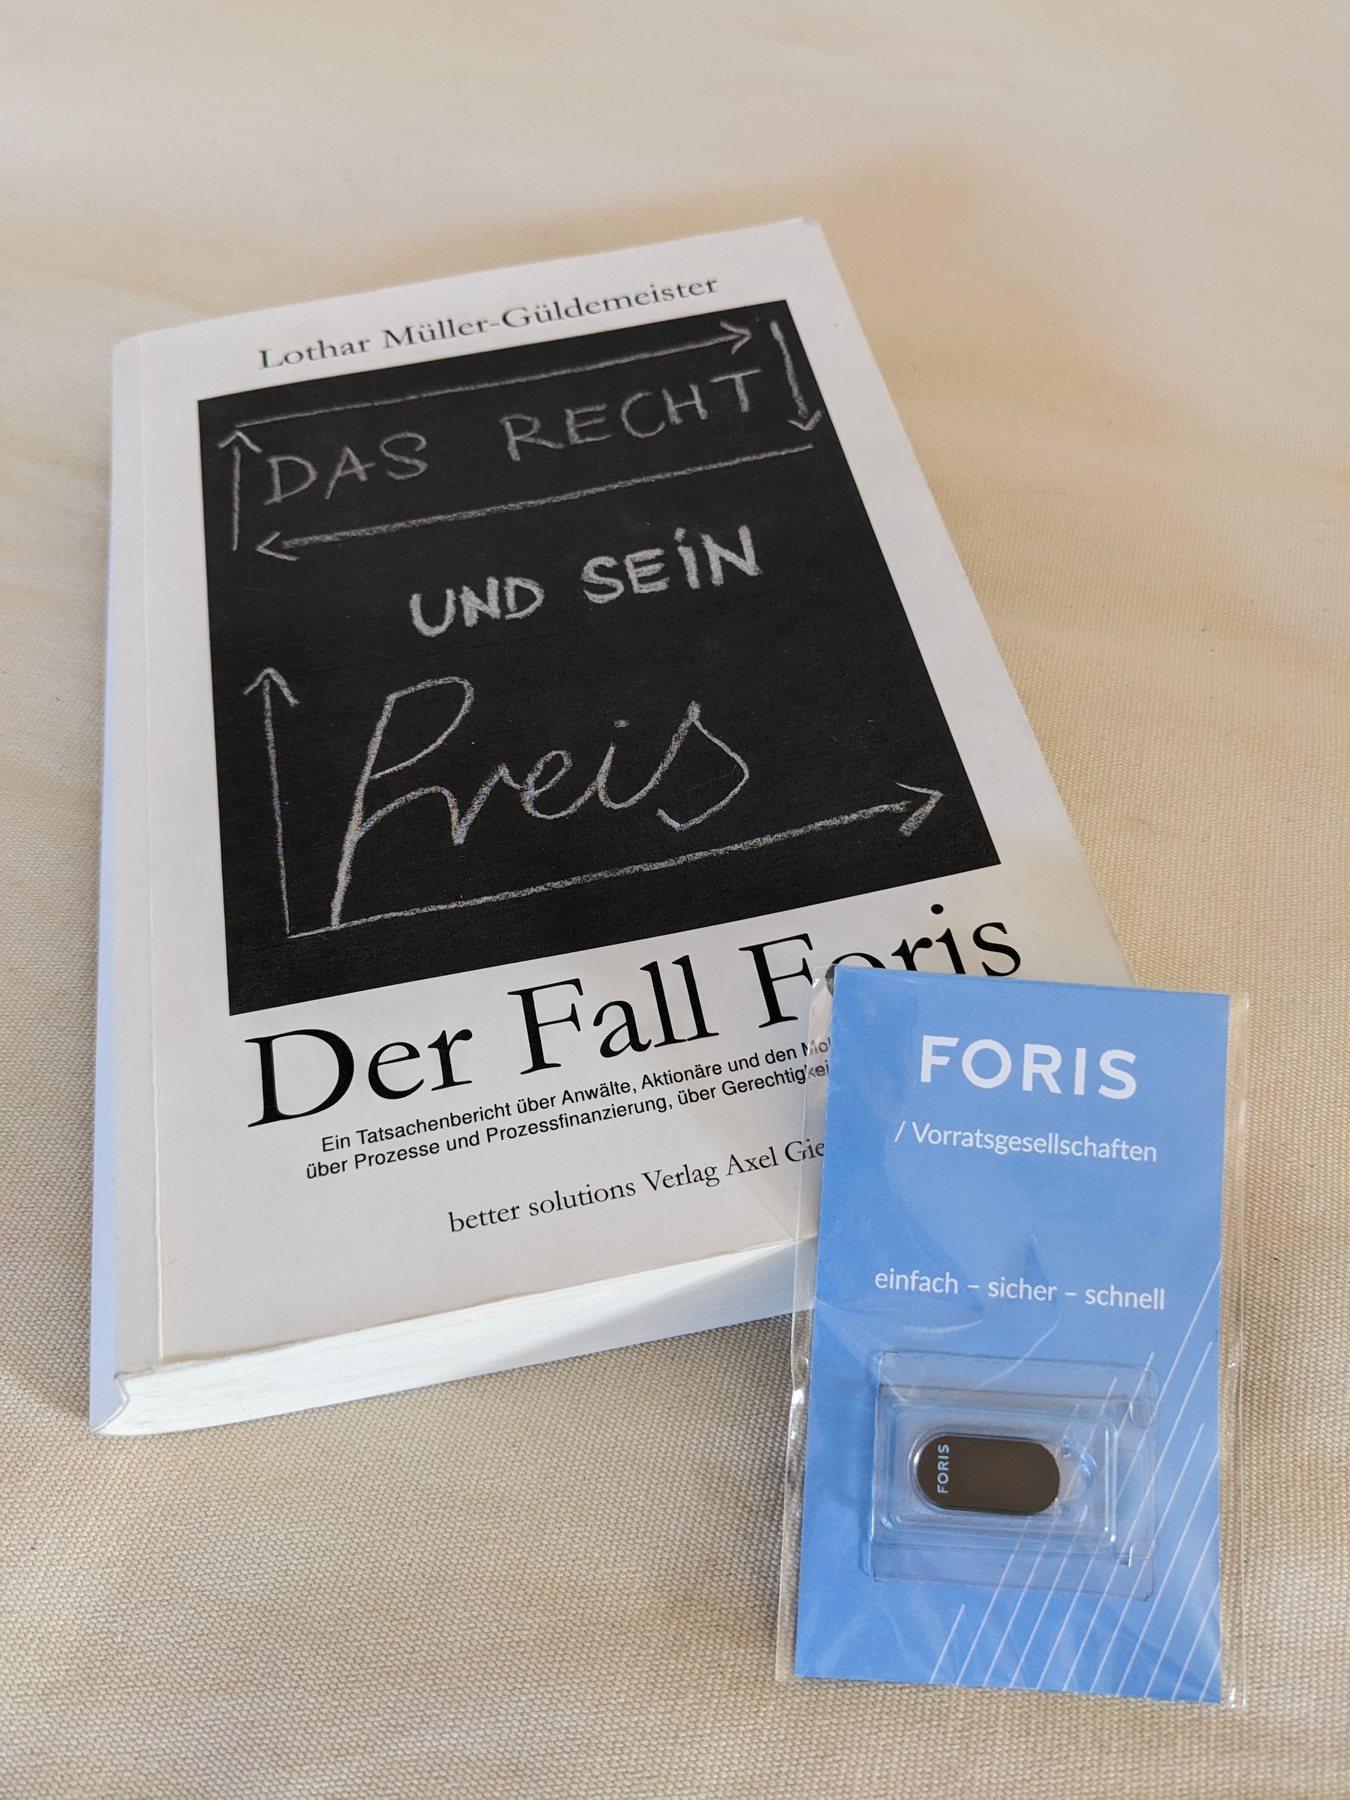
Here is a rarity for the museum: an exhibit that was destroyed not because the idea was bad, but because it was too good, too early, and listed in the wrong place. FORIS AG – founded in Berlin in 1996 and today based in Bonn – deserves a moment of genuine respect before the usual mockery resumes.
In 1998, Foris pioneered commercial litigation funding in Germany: it would pay the costs of pursuing a lawsuit – lawyers, court fees, the lot – in exchange for a share of the winnings if the case succeeded, typically around 30 per cent. For the claimant, risk transferred; for Foris, a return stream with nothing to do with the stock market. It was, genuinely, a clever and modern idea – clever enough that the big insurers soon copied it. From 2002 Allianz ran its own litigation funder, Allianz ProzessFinanz, in direct competition. Imitation is the sincerest form of margin pressure.
Then it made the one fatal decision available to a clever idea in 1999: it floated on the Neuer Markt, Germany’s Nasdaq-cosplay growth exchange, in the white heat of the dot-com mania. The shares were first quoted on 19 July 1999 at an issue price of €45, raising some DM 29 million. For a moment this was wonderful. The Neuer Markt did not ask awkward questions about profits; it asked only for a story, and “we fund lawsuits for a cut” was a fine story.
The 1999 annual report, in hindsight, carries the warning in plain figures: a loss of €0.62 per share, inflated by the costs of the flotation itself, with an operating loss underneath – the unmistakable profile of a company valued for its narrative rather than its earnings. Which was fine, right up until narratives stopped being legal tender.
When the Neuer Markt collapsed – its index lost over 96 per cent, and the segment was quietly closed in 2003 – Foris’s shares went down with the ship. In August 2001 the company was among those that went to court against the exchange’s new rule to expel penny stocks, winning a six-month reprieve. A litigation funder suing its own stock exchange has a certain professional logic – but it is rarely a sign that the share price is doing well.
The company itself did not vanish; it survives today, quietly, as a small and real business listed in Frankfurt. Most of its revenue now comes, a little ironically, from selling ready-made shelf companies rather than from funding lawsuits, and at the end of 2025 the whole enterprise was valued at about €16 million – roughly what it raised at its IPO. But the share, as a Neuer Markt artefact, belongs here.
And the cosmic punchline, which the museum cannot resist: litigation funding turned out to be a superb business. An entire global asset class now does exactly what Foris pitched in 1998. Burford Capital, founded in 2009, became its poster child – not least through its stake in a $16.1 billion US judgment against Argentina over the nationalisation of YPF. Foris was right about everything except the two things that actually mattered to its share price: the decade, and the stock exchange.
Museum note: the asset class has since learned the Foris lesson in its own way. In March 2026 a US appeals court overturned the YPF judgment, and Burford’s shares fell 42 per cent in a day. Lawsuits, it turns out, are uncorrelated with the stock market – but not with the court of appeal.
Further reading
- FORIS AG – Annual report 1999 (German) (2000)
- FORIS AG – About us
- Tagesspiegel – Foris wins a reprieve from the penny-stock rules (2001)
- Stiftung Warentest – Litigation funders: companies take on the risk (2008)
- Wikipedia (German) – Neuer Markt
- Wikipedia – Burford Capital
- AJ Bell – US appeals court overturns YPF judgement against Argentina (2026)